Pension Decisions
Pension Decisions
This Choice Doesn't Get a Do-Over
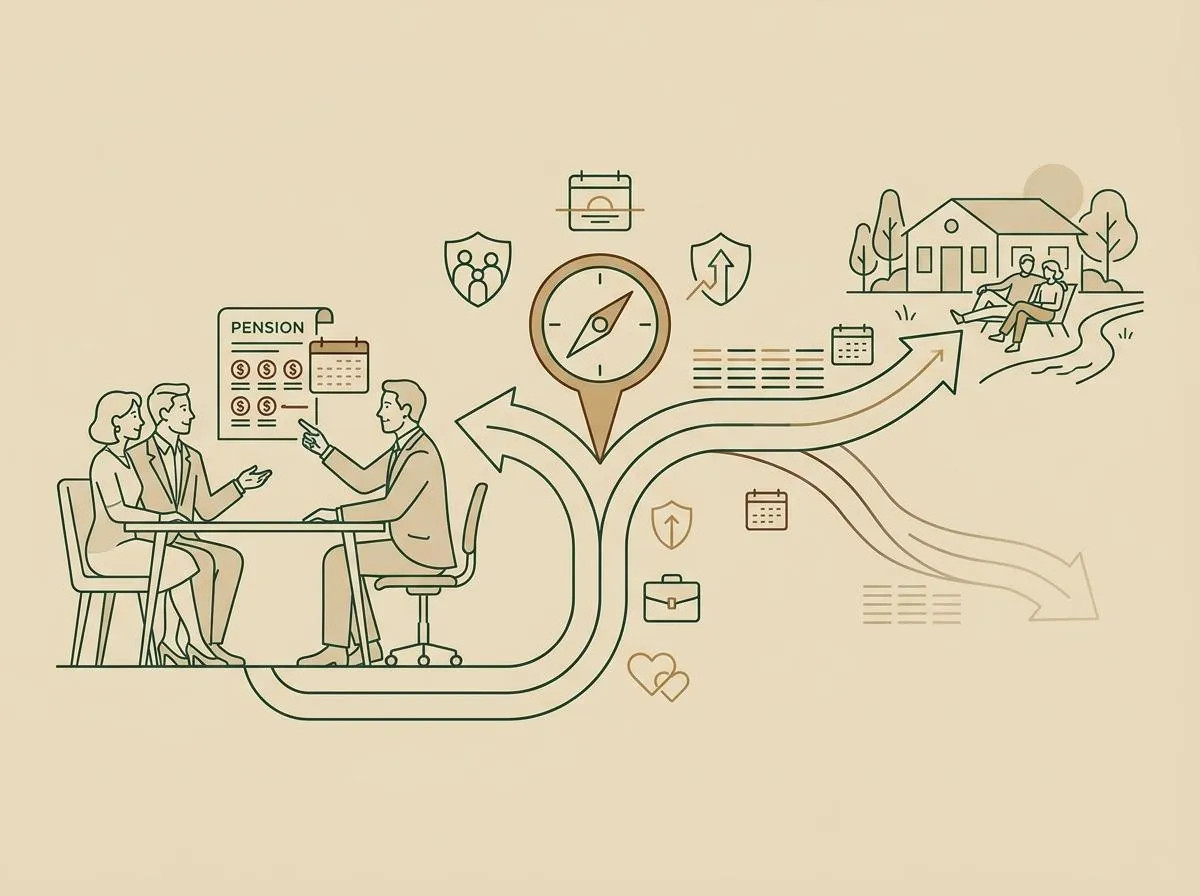
Once you elect a lump sum or a monthly pension, that election is generally final — there's no switching back if your circumstances change five years later. At Flintridge Private Wealth, we make sure you're deciding with the full picture in front of you, not just the two numbers on the election form.

Forbes Best-In-State Wealth Advisor
2024, 2025, 2026
Selected based on a combination of qualitative and quantitative criteria, including industry experience, client service, and assets under management. No fee was paid for consideration. Learn More.

Five Star Wealth Manager
2025, 2026
Award recipients are selected based on objective criteria, including client retention, industry experience, assets under management, and a regulatory review. No fee is required for consideration. Learn More.
#2 on Barron's as Top 100 RIA Firms
2026
Barron’s rankings awarded in September 2026 based on prior 12-month data. NewEdge Capital Group is the award recipient. Flintridge Private Wealth and NewEdge Capital Group, LLC are not affiliated entities. Learn More.

#8 on Forbes as America’s Top RIA Firms
2025
Forbes/Shook rankings awarded in October 2025 based on data from 3/31/24-3/31/25. NewEdge Capital Group is the award recipient. Flintridge Private Wealth and NewEdge Capital Group, LLC are not affiliated entities. Learn more.
Flintridge Private Wealth is a fee-only fiduciary advisory firm.
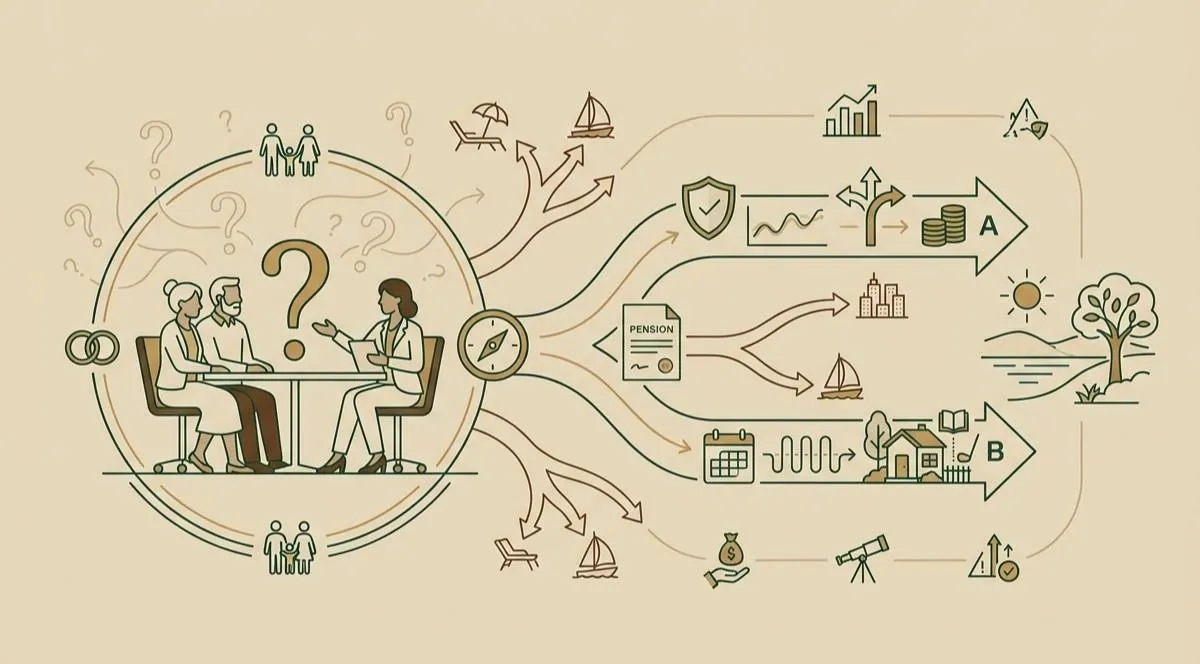
Common Questions We Hear Every Day
● "What if the monthly pension doesn't keep up with inflation over the next 20 years?"
● "Should I really take the lump sum right before the market tanks?"
● "If I go with the pension and something happens to me, does my spouse keep getting paid?"
● "Everyone I know seems to be doing something different — how do I know which one's actually right for me?"
● "What if I make this decision and realize in five years it was the wrong call?"
None of these questions have a one-size answer — that's exactly why we walk through them one at a time instead of handing you a generic recommendation.
How We Help You Decide
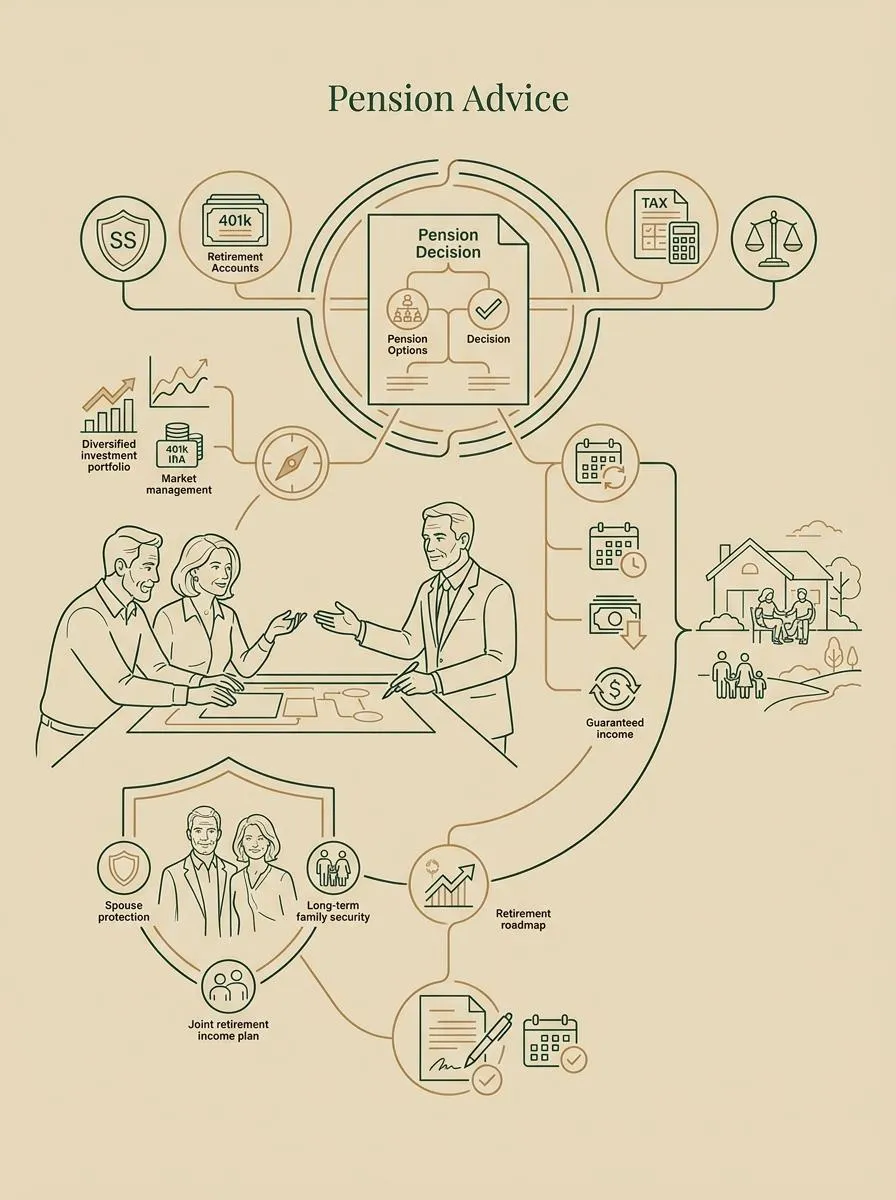
Pension decisions are rarely as simple as choosing between a monthly income and a lump sum. We evaluate the decision within the context of your entire financial picture.
We typically start with your income needs and retirement objectives, then look at the pension's guarantees, payout options, survivor benefits, inflation considerations, and the financial strength of the plan itself. From there, we compare the pension against the opportunity cost and flexibility of taking a lump sum and investing those assets instead.
We also factor in taxes, Social Security, other income sources, portfolio risk, longevity, liquidity needs, and your estate-planning goals.
The real question we're answering: which option creates the most reliable, flexible retirement-income strategy for you specifically? There's no universal answer — it depends on your goals, risk tolerance, health and longevity, and the role the pension needs to play in your broader plan.
How We Work Through It With You
Our pension planning process
1. Understand Your Income Needs
We start with your retirement objectives and what income you'll actually need.
2. Evaluate the Pension Itself
Guarantees, payout options, survivor benefits, inflation protection, and the strength of the underlying plan.
3. Compare Against the Lump-Sum Alternative
The opportunity cost and flexibility of investing those assets instead.
4. Factor In the Full Picture
Taxes, Social Security, other income, portfolio risk, longevity, and estate goals — all considered together.
Why Clients Choose Us for This Decision
This Isn't the First Time We've Done This
A pension election happens once. We've walked hundreds of people through that same one-time decision, which means we've already seen most of the ways it can go right or wrong.
● We've sat across the table from people in almost every version of this decision — different pension sizes, different health situations, different marriages.
● We can tell you honestly when a lump sum is probably the wrong move for someone, not just when it's the right one.
● Every recommendation gets checked against your Social Security timing, your other accounts, and your tax situation — not made in isolation.
● Your spouse's outcome gets built into the plan from the start, not added as an afterthought once you've already decided.
● We stay involved through the actual paperwork and election deadlines, so a missed date doesn't undo months of planning.
Office Location
Visit Our Pasadena Office
Meet with the Flintridge Private Wealth team for personalized financial guidance and wealth management services tailored to your goals.
Pasadena Office
Flintridge Private Wealth
251 South Lake Avenue
Suite 800
Pasadena, CA 91101
Mon - Fri: 9:00 AM to 5:00 PM
Our Approach
Our Approach
QUICK LINKS
Check the background of your financial professional on FINRA's BrokerCheck.
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. Please consult legal or tax professionals for specific information regarding your individual situation. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security.
Advisory services offered through NewEdge Advisors, LLC, a registered investment advisor.
NewEdge Advisors, LLC (“NewEdge Advisors”) is a registered investment advisor. Advisory services are only offered to clients where NewEdge Advisors and its representatives are properly licensed or exempt from licensure. This website is solely for information purposes. Past Performance is no guarantee of future returns. Investing involves risk and possible loss of principal capital. No advice may be rendered by NewEdge Advisors unless a client service agreement is in place.
© Copyright 2026 Flintridge Private Wealth. All Rights Reserved. Web Design By GenieBoost.